Almost nothing is as important to someone today as their financial health. Most of us want to stay on top of what's happening with our bank accounts, like when a deposit clears so we can pay bills, if we're reaching our credit card limit, or if we have finally paid off that 30-year mortgage and can free up funds for that dream vacation or paying for our kid's college tuition. But we don't always get immediate feedback when transactions happen. That information often sits on the backend within our banks, and then days or weeks later we may get an email or alert with advice on investing or creating a payment plan.
But with actionable banking, this all becomes immediate. With the help of agentic AI, banks’ customers can quickly have a better understanding of steps they can take to make an investment or curb their spending with AI-powered insights. And people have said they want this.
In fact, in a survey conducted by Personetics of 2,000 bank customers(1), 70% said they strongly want their bank to proactively analyze their financial situation and 84% said they would likely switch to a bank that offers timely, relevant advice.
Actionable banking is also the safest first step toward autonomous banking. The agents act on events, but a human still makes the decision. MongoDB Atlas makes this possible by turning banking events into real-time triggers, unifying customer context in one platform, and keeping an auditable record of every agent action.
A three-step ladder: From passive to autonomous banking
Actionable banking serves as the bridge between legacy banking and fully autonomous finance:
Figure 1. The three-step ladder from passive to autonomous banking.
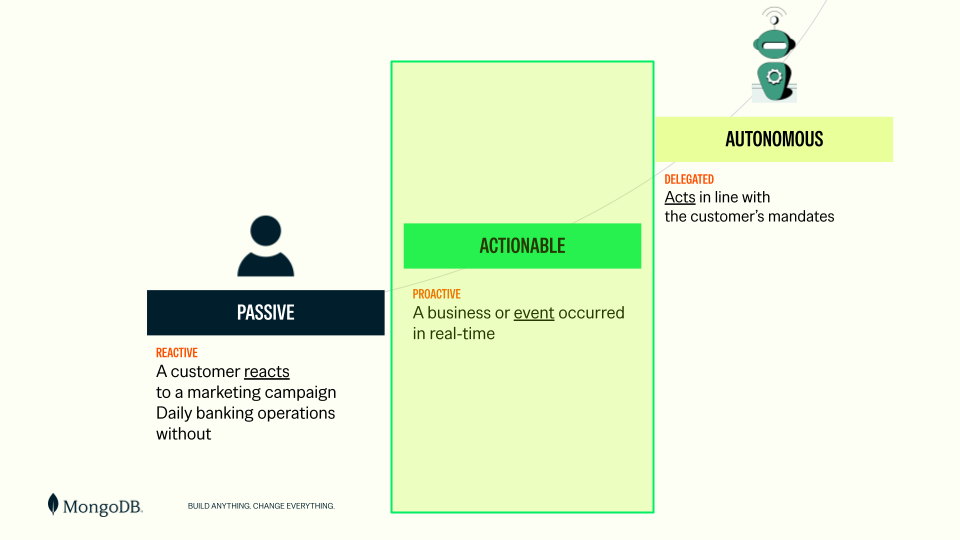
- Passive banking: The customer initiates the interaction, most likely in response to a marketing campaign.
- Actionable banking: The bank takes a proactive approach based on real-time event analysis. Agents act on events, but the customer still makes the decision.
- Autonomous banking: A personal finance agent acts on its own, within limits the customer has set in advance and can revoke at any time.
The gap between actionable and autonomous is not the model. It is evidence: A bank can only grant agents a mandate once it can show what each agent saw, decided, and did, and who authorized it. Actionable banking is how that evidence gets logged into the corresponding audit trail.
Actionable banking also imposes a behavioral change. A dedicated agent will be continuously monitoring personal banking information, so its success will depend heavily on the guardrails implemented by the bank, in line with the customer's consent. More importantly, it should comply with data protection and AI regulations. Policymakers are moving fast to propose frameworks that incentivize innovation with the right controls in place. In the end, actionable banking's goal is to recommend the "best course of action" based on specific triggered events, but the customer is the one who decides and has the final word, which safeguards trust.
Below are three actionable agentic workflows and a reference architecture built on MongoDB Atlas and Atlas Agent Engine.
Three banking events, three agentic workflows
Every workflow starts with the Personal Finance Agent, which listens to daily banking activity through event-driven notifications. When a significant event arrives—a large deposit, an overdue card balance, a new mortgage—the agent opens an agentic workflow, hands the work to specialist agents, and returns a proposal the customer can discuss.
Figure 2. Actionable agentic workflow for proactive investments.
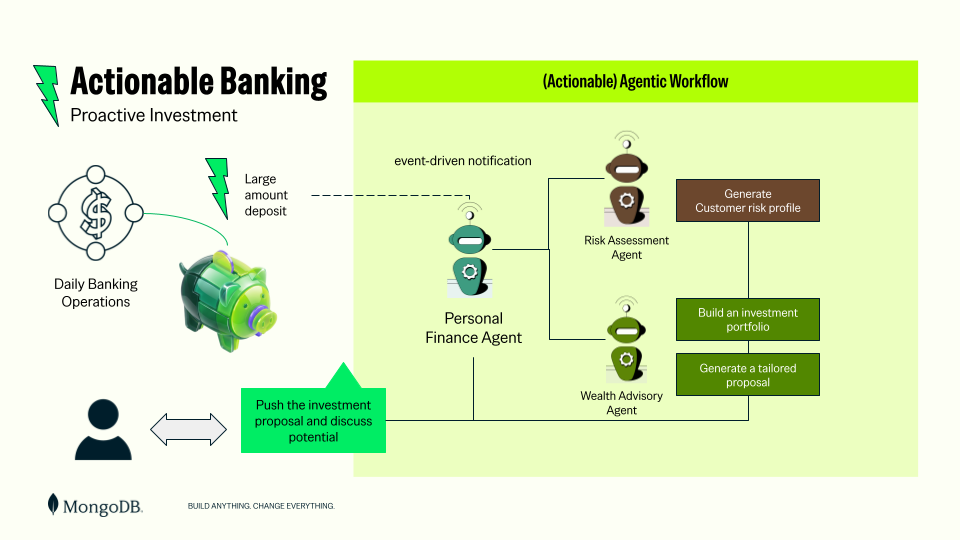
Proactive investment. A large deposit is the clearest signal of idle money. McKinsey estimates(2) that $23 trillion of the $170 trillion in consumer deposits worldwide sits in accounts paying zero or close to zero interest. The risk profile is not a formality; the EU requires the MiFID II suitability assessment before investment advice. So a risk assessment agent's output must be stored as evidence, not just passed along in a prompt. While the personal finance agent is responsible for the interaction and agreement with the customer, the wealth advisory agent is specialized in private banking, bringing the right proposal to the customer.
Figure 3. Actionable agentic workflow for proactive lending.
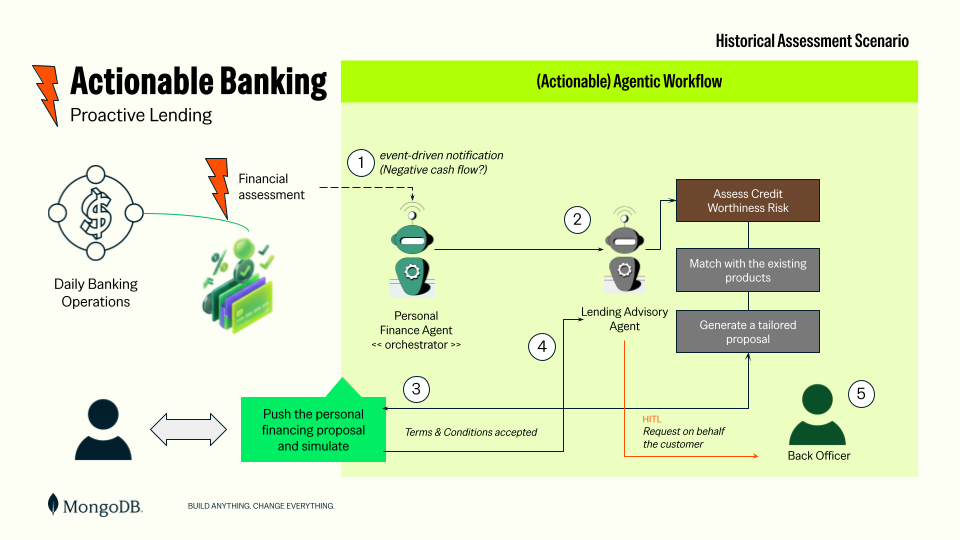
Proactive lending. An overdue card balance is both a credit risk and a moment of customer stress. Moving the balance to a cheaper installment loan costs the bank card margin, but keeps the customer and lowers its credit risk. Creditworthiness assessment of individuals is a high-risk use under the EU AI Act, so this workflow needs the strictest human oversight of the three. A credit risk officer needs to review, approve, and have all the arguments at hand for situations where customers and regulators would demand an explanation. A single agent with lending expertise can handle both risk assessment and advisory.
Figure 4. Actionable agentic workflow for proactive added-value services.
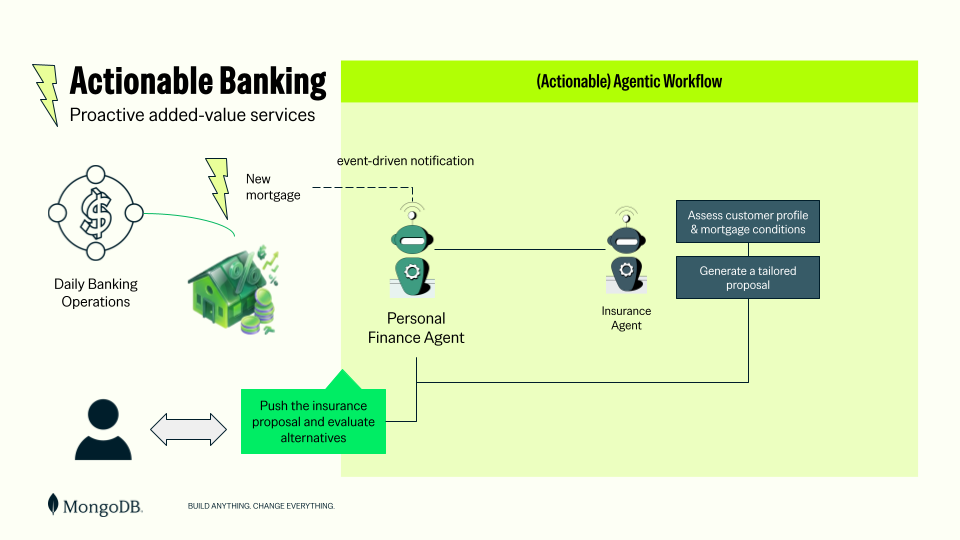
Proactive added-value services. A new mortgage changes the terms of what the customer needs to protect. The insurance agent reads the mortgage conditions and proposes an insurance policy with the proper coverage, as an optional offer and never as a condition of the loan.
Each workflow ends in "push and discuss," not "execute." That is what makes it actionable rather than autonomous.
Actionable banking reference architecture on MongoDB
Figure 5. Actionable banking reference architecture.
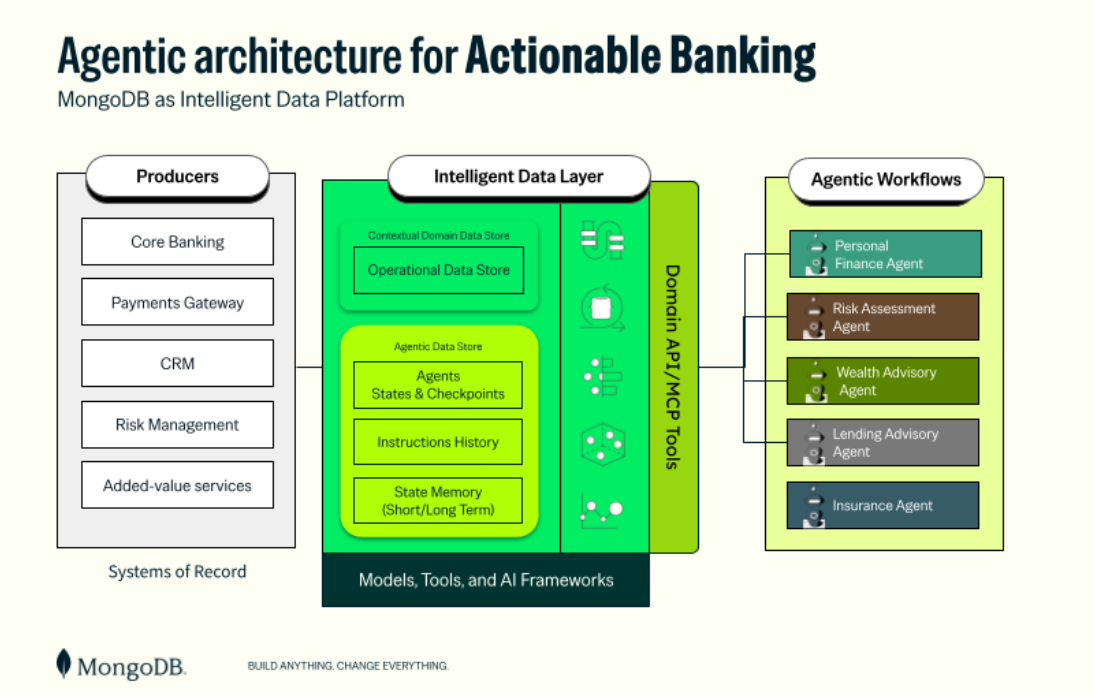
Systems of record write into MongoDB Atlas, which holds the operational view of each customer. Change streams turn business moments into events for the personal finance agent. Specialist agents run on Atlas Agent Engine, sharing customer context through a common memory layer with per-agent access controls. Every agent action and tool call is recorded in a single, immutable audit trail. The customer's decision flows back as memory for the next interaction and as evidence for the regulator.
The business case for actionable banking
McKinsey(3) estimates that banks that fail to adapt to agentic AI could see global profit pools fall by about $170 billion, or roughly 9%, as customers' own agents start moving idle money. Actionable banking is both the defense and the offense: The bank's agent makes the better offer before someone else's agent does.
Why banking agent projects stall and what the platform must fix
Banks are not short of agent pilots; they are short of agents in production. Gartner(4) expects over 40% of agentic AI projects to be canceled by the end of 2027 over cost, unclear value, or weak risk controls. Actionable banking runs into three engineering problems behind those numbers.
Atlas Agent Engine(5), in public preview since September of 2026, unifies runtime, memory, and governance in one layer, with sandboxed execution and agent identity built in. It is neutral across models and frameworks and built on open standards such as MCP and A2A, so a personal finance agent can delegate to specialist agents without tying the bank to one vendor's model or cloud. Paysafe is already exploring an agent engine-based agent so its analysts stop stitching together data from multiple systems by hand when investigating unusual payment activity.
A change in behavior, not only in technology
Actionable banking is largely an engineering pattern. Autonomous banking also requires a shift in trust and behavior. Customers must delegate, banks must accept accountability for agents that act, and regulators must be satisfied that both are safe.
The relationship manager becomes an agent. The attention of a private banker, someone who notices the bonus, the new mortgage, and the missed payment, has always been rationed by cost. A personal agent makes it available to every customer, around the clock, with memory of every conversation. Banks that get this right keep the relationship with the customer. Those that don’t may end up as the infrastructure for another party’s agent.
Trust is the ultimate mandate. The most critical challenge is not technical. Delegating decision-making authority to an agent—and granting it permission to act on behalf of an organization or an individual—turns machines into active economic participants. That is a disruptive behavioral change for customers, regulators, and banks alike. Banks have always sold trust; in autonomous banking, they must also prove it, action by action and mandate by mandate.
Start simply with one event, one workflow, or one governed proposal. That is the first step toward autonomous banking, and the data platform underneath decides how far you can take it.
Next Steps
Head over to MongoDB University to learn how to build and deploy AI agents using MongoDB.
To see how financial institutinos are building the data layer that makes AI agents safe to trust, read Systems of Action: Building the AI Era.
Sources:
- (1)New Research Shows Surging Consumer Demand for AI-Banking Services, According to Personetics Global Survey
- (2)Customer use of AI agents will depress profits: McKinsey | American Banker
- (3)Bank profits face $170bn hit from AI - McKinsey
- (4)Gartner Predicts Over 40% of Agentic AI Projects Will Be Canceled by End of 2027
- (5)MongoDB Launches Atlas Agent Engine to Put AI Agents in Production Without a New Stack